The elderly Black man entered the bank carrying forty dollars in one hand and a worn passbook in the other.
That was all anyone in the lobby could see.
No tailored suit.
No driver waiting at the curb.
No watch worth more than a house.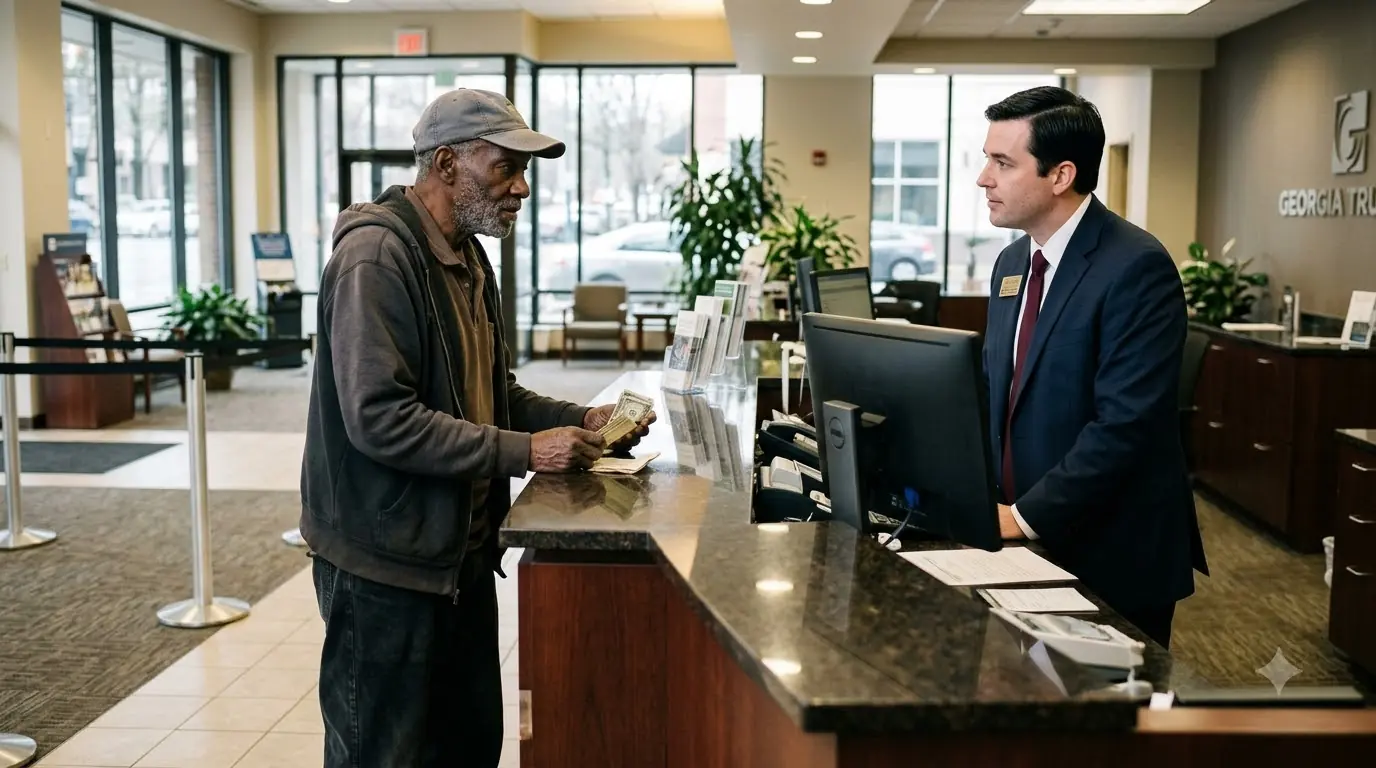
No assistant.
No security detail.
Just a seventy-eight-year-old Black man with a short gray beard, a faded baseball cap, a charcoal hoodie that had been washed enough times to lose its original color, old jeans, and work shoes whose soles had begun to separate near the toes.
He walked slowly.
Not because he was weak.
Because his left knee had reminded him every morning for the past nine years that cartilage did not negotiate.
The branch manager noticed him before the elderly man had crossed half the lobby.
That was the first important thing.
The second was the expression that appeared on the manager’s face.
Not concern.
Not recognition.
Assessment.
The manager stood behind the polished customer-service counter wearing the bank’s formal navy uniform: fitted blazer, crisp white shirt, burgundy tie, polished shoes, and a silver management badge pinned precisely over his chest.
He was forty-three, white, clean-shaven, meticulously groomed, and proud of the branch in a way that had gradually blurred into believing the branch belonged to him.
He looked at the old man’s hoodie.
Then the cap.
Then the forty dollars.
Then he leaned toward the assistant manager and murmured something.
The assistant manager smiled.
The elderly man noticed.
He noticed nearly everything.
That was partly age.
Mostly training.
For fifty-four years, banking had taught him that people revealed themselves most clearly when they believed nobody important was watching.
He had spent the first twenty-nine years of his career moving through teller cages, loan departments, audit teams, branch acquisitions, and crisis restructurings.
He had spent the next twenty-five leading institutions.
At seventy-eight, he was chairman and chief executive officer of the very bank whose marble floor he was now crossing in worn shoes.
Nobody in the branch knew.
That was intentional.
Three weeks earlier, an envelope had arrived at corporate headquarters.
No return address.
Inside were photocopies of eleven deposit receipts.
All belonged to customers over sixty-five.
Every deposit had been cash.
Every receipt had shown one amount.
Every account statement later reflected a smaller amount.
The differences were small enough to hide.
Forty dollars.
Sixty.
One hundred.
Two hundred.
Never enough, apparently, to trigger the kind of automatic fraud alert designed for large losses.
Enough to matter to the people losing it.
The anonymous letter contained one sentence.
Ask why the old customers keep being told they counted wrong.
The CEO had read that line four times.
Then he called the head of internal audit.
By the end of the day, they had twelve additional complaints.
Not all substantiated.
Some were memory mistakes.
One was a bank error corrected months earlier.
But six contained a pattern.
Same branch.
Same manager override codes.
Same end-of-day cash adjustments.
And, most troubling, the same customer profile.
Older.
Often alone.
Often making cash deposits rather than electronic transfers.
Some spoke slowly.
Some had difficulty hearing.
Two had limited English.
One had mild cognitive impairment documented by her daughter.
A compliance analyst had already flagged the branch twice.
Both alerts had been closed after the manager submitted explanations.
“Customer counting error.”
“Duplicate receipt.”
“Cash discrepancy reconciled.”
“Customer confused denomination.”
Each explanation sounded plausible.
Until they accumulated.
The CEO had spent his career distrusting patterns that were too convenient.
He did not announce an investigation.
He did not call the manager.
He did not send security first.
Instead, he asked a question.
“If somebody is taking cash,” he told internal audit, “what do they believe allows it to continue?”
The senior auditor answered immediately.
“They believe the customers won’t be believed.”
The CEO nodded.
“Then we need to see what happens before they know they’re being watched.”
The audit team designed a controlled test.
An elderly widow who had filed two previous complaints agreed to participate.
She was seventy-four.
Black.
Retired cafeteria supervisor.
She had banked at that branch for seventeen years.
She had deposited $600 two months earlier and received only $500 credit.
The manager had told her she must have miscounted.